How the Saudi-Houthi Escalation Threatens Global Oil Supplies

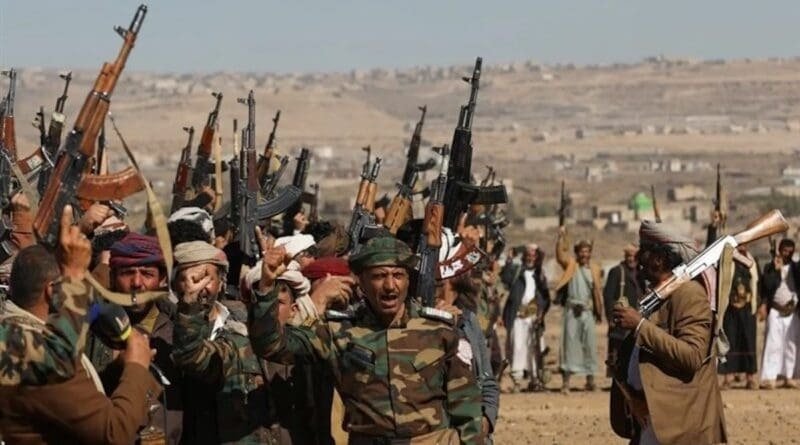
The escalating military confrontation in Yemen is no longer simply another chapter in the region’s prolonged conflicts. It is increasingly carrying direct consequences for global energy markets. As Houthi attacks on Saudi-linked interests and infrastructure intensify, concerns are growing that the conflict in Yemen could become an additional source of pressure on global oil supplies at a time when markets are already facing major disruptions caused by the war between the United States and Iran and growing tensions around the region’s most important energy corridors.
The danger of the latest developments lies in the fact that three critical energy arteries could potentially be disrupted at the same time: the Strait of Hormuz, the Bab al-Mandab Strait, and Saudi Arabia’s East-West oil pipeline. Any prolonged disruption to these routes could increase transportation costs and intensify concerns over the availability of supplies, with rapid repercussions for oil prices and the global economy.
Oil Caught Between Two Fronts: Iran and Yemen
Oil prices have risen significantly amid the escalation of tensions. The price of crude reached around $110 a barrel on September 15, its highest level in several months, before easing slightly.
But the increase is not solely linked to the escalation in Yemen. Energy markets are simultaneously dealing with the consequences of the US-Iran war, which has effectively closed or severely restricted shipping through the Strait of Hormuz, one of the world’s most important arteries for oil and gas trade.
Against this backdrop, Gregory Brew, an oil expert and analyst at the Eurasia Group, argues that energy markets are being affected by a dynamic involving two simultaneous conflicts: the Saudi-Houthi conflict on one side and the US-Iran conflict on the other.
This means that pressure on oil markets is not coming from a single source, but from several strategic chokepoints at the same time.
This is precisely what makes developments in Yemen more significant than their immediate military scale might suggest. Even if the fighting remains geographically contained, its economic impact could extend far beyond Yemen and Saudi Arabia and reach global markets.
The East-West Pipeline: A Vulnerable Alternative Route
One of the most significant sources of concern is Saudi Arabia’s East-West oil pipeline, an important route for transporting crude from the kingdom’s production areas in the east to its ports on the Red Sea.
Its strategic importance becomes even greater as disruptions affect the Strait of Hormuz. The more difficult it becomes to move oil through Hormuz, the more important alternative export routes through the Red Sea become for Saudi Arabia.
Yet damage to this route has reduced the kingdom’s ability to export oil, according to the report, while the timeline for restoring the pipeline remains unclear.
Estimates from commodity intelligence firm Kpler suggest that if the pipeline remains out of service for a month, approximately 120 million barrels of oil could be lost from global supply flows.
This creates a fundamental paradox: the route intended to serve as an alternative to the Strait of Hormuz is itself vulnerable, limiting the ability of the world’s largest oil exporter to compensate for disruptions elsewhere.
Bab al-Mandab: Another Strategic Chokepoint
Alongside the pipeline, the Bab al-Mandab Strait has emerged as another critical pressure point.
The strait, which connects the Red Sea with the Gulf of Aden and the Indian Ocean, is a major route for commercial shipping and oil tankers. According to the report, around 6 percent of the world’s seaborne oil trade passes through the area.
Any attempt to close Bab al-Mandab or significantly disrupt shipping through it for an extended period would therefore have consequences far beyond the Yemeni conflict itself.
The alternative for shipping companies would not necessarily be to halt trade altogether, but to reroute vessels around longer routes. That would increase transportation and insurance costs, lengthen delivery times, and add further pressure to energy prices.
The Houthis have reportedly assured Washington that they will not target international shipping or close Bab al-Mandab, with Saudi vessels being the exception. Yet as long as military operations continue, the possibility that the confrontation could widen remains, particularly if the calculations of the various parties change.
Saudi Arabia Faces a Complex Security Equation
For Riyadh, the latest developments represent a major setback after years of military involvement in Yemen.
Saudi Arabia entered the war in 2015 in support of Yemen’s internationally recognized government after the Houthis seized large parts of northwestern Yemen, including the capital, Sanaa. After years of military operations, the kingdom now faces multiple security challenges as the ability of its local allies to hold territory has weakened in the face of Houthi advances.
The pressure does not come from the Houthis alone. Saudi Arabia is also facing threats from other armed groups in the region that are linked, to varying degrees, to Iran.
Saudi territory is therefore becoming an increasingly important part of the regional conflict equation: oil facilities on one side, export infrastructure on another, and maritime routes close to the kingdom on a third.
Why Does Washington Not Want Another War in Yemen?
While Riyadh has requested greater US military support, the developments described in the report suggest that the administration of President Donald Trump has not responded to those requests in the manner Saudi Arabia had hoped.
Part of the US calculation appears to be linked to avoiding a new military front in Yemen, particularly as Washington is already engaged in a confrontation with Iran.
Thomas Juneau, a Middle East expert and professor at the University of Ottawa, describes the US position as strategically straightforward: the United States is already confronting Iran in the Gulf, and entering another major war in Yemen could turn the conflict into a military and political quagmire that would be difficult to escape.
The Houthis, meanwhile, have their own calculations. They faced an intense US bombing campaign in 2025, forcing them to absorb significant military costs. Reaching limited understandings with Washington could therefore give them additional room to maneuver while maintaining pressure on Saudi Arabia.
This helps explain why the current situation appears closer to a process of managed escalation among the various parties than to an all-out regional war.
Could Oil Reach $120 a Barrel?
The most concerning scenario for markets is the continuation of energy disruptions across several fronts simultaneously.
If the East-West pipeline remains disrupted, maritime traffic through the Strait of Hormuz continues to face restrictions, and threats to shipping in the Red Sea and around Bab al-Mandab expand, markets could face a problem involving not only the amount of oil available but also the ability to transport it from production centers to consumers.
Goldman Sachs has warned that global oil prices could reach $120 a barrel if the conflicts in Iran and Yemen continue.
The significance of this figure, however, does not lie in its being an inevitable forecast. Rather, it reflects the market’s sensitivity to accumulating geopolitical risks.
Oil markets do not necessarily wait for an actual physical shortage to occur before prices rise. In many cases, the growing probability of a supply disruption is enough to increase the risk premium embedded in prices.
From a Local Crisis to a Global Crisis
The latest developments in Yemen highlight the changing nature of regional conflicts in the Middle East. The importance of a conflict is no longer measured solely by the territory controlled by one side or by the scale of military operations. It is also measured by its ability to disrupt global energy and trade infrastructure.
The current situation brings together three highly sensitive factors: the US-Iran war, the Saudi-Houthi escalation, and growing disruption along energy and shipping routes in the Gulf and Red Sea.
If these factors continue to reinforce one another, global markets could become increasingly vulnerable to successive shocks in prices and supply.
Higher energy costs could also feed into transportation, industrial production, electricity prices, and consumer goods, adding to inflationary pressures in oil-importing economies.
The question, therefore, is no longer simply whether the Houthis can threaten Saudi Arabia. It is also how far a geographically limited conflict can reshape the global flow of energy.
Conclusion: A Battle Over Routes as Much as Territory
The confrontation in Yemen is entering a phase that goes beyond traditional military calculations. Attacks on energy infrastructure and oil-export routes give the conflict an economic impact far greater than its geographical scope.
For Saudi Arabia, risks to the East-West pipeline are emerging alongside threats to shipping routes in the Red Sea, while the Strait of Hormuz is facing extraordinary pressure because of the war with Iran.
For the United States, avoiding deeper involvement in a large-scale Yemen war appears to be linked to an effort to prevent the regional conflict from expanding at a time when multiple fronts are already active.
Ultimately, global oil markets are likely to be where the consequences of these developments become visible most quickly. The greater the number of energy facilities and transportation routes exposed to attack, the higher the geopolitical risk premium becomes, leaving the global economy more sensitive to any new attack or additional disruption.
The future of oil prices, therefore, will not be determined solely by what happens in production fields. It will also depend on what happens along the routes that carry oil from those fields to global markets.
Most read

Read also